Interest rate volatility demands more than strong balance sheet controls. Tihomir Bublic argues that resilience depends on strategic agility, disciplined optionality, stronger deposit relationships, and making interest rate risk management an integral par
The prolonged uncertainty surrounding
interest rates has fundamentally changed how financial institutions should
think about balance sheet management.
Rather than attempting to predict the
next move in monetary policy, banks should focus on building resilient balance
sheets capable of performing under multiple scenarios while embedding interest
rate risk into strategic decision-making.
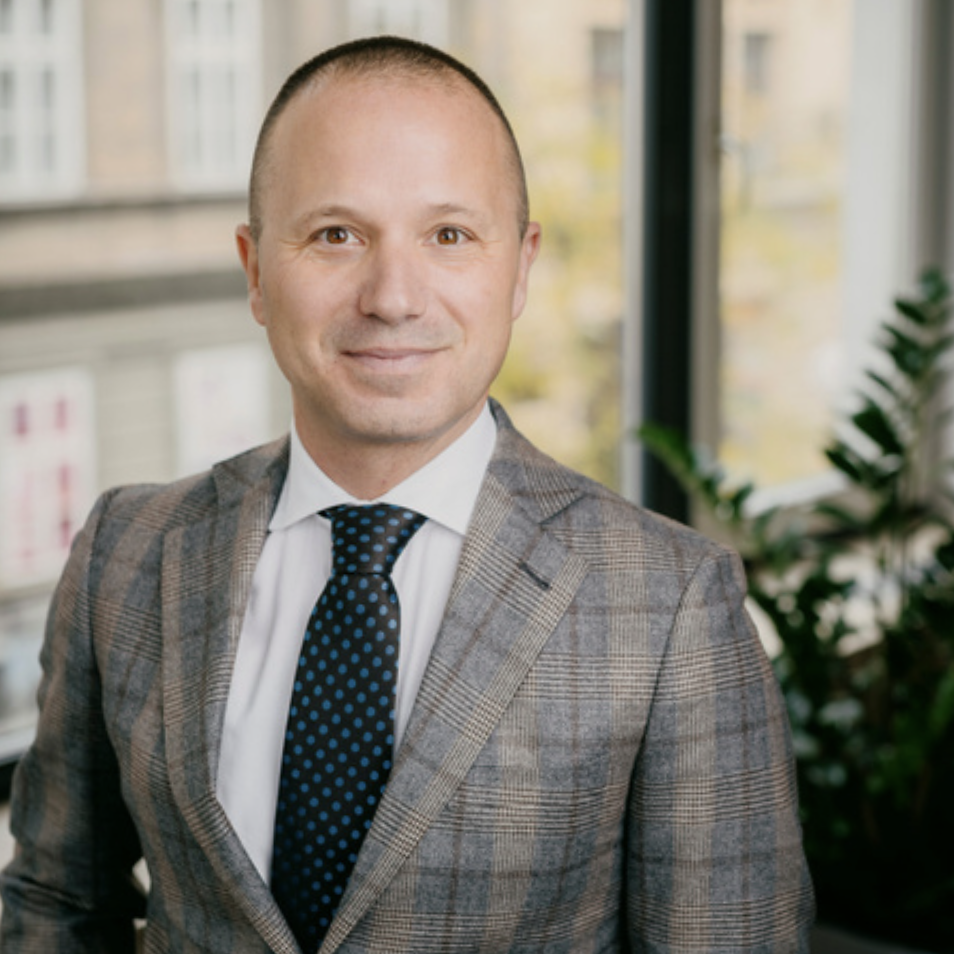
That is the view of Tihomir Bublic,
Director of Asset Liability Management at Hrvatska Poštanska Banka, Croatia,
who believes institutions must move beyond conventional approaches if they are
to remain competitive in an increasingly unpredictable environment.
For Bublic, resilience begins with
acknowledging that traditional stress testing is no longer sufficient.
Institutions need a far broader understanding of how different interest rate
environments could affect both sides of the balance sheet.
"Resilience requires
stress-testing across a range of scenarios - not just parallel shifts, but
steepeners, flatteners, and inversions," he says.
He believes banks must also avoid
becoming overly exposed to long-duration fixed-rate assets unless those
positions are appropriately hedged.
At the same time, liability
management requires a much deeper understanding of customer behavior than
contractual assumptions alone can provide.
"On the liability side, invest
in genuinely understanding deposit behaviour rather than relying on contractual
repricing dates," Bublic explains.
Many organizations continue to
underestimate some of the structural weaknesses embedded within their balance
sheets. According to Bublic, these vulnerabilities often stem not from market
movements themselves but from unrealistic assumptions used to manage them.
"The most common vulnerabilities
arise from overly optimistic deposit beta assumptions, underestimated
optionality in assets and liabilities, and a disconnect between the IRRBB
framework and actual business strategy," he says.
That strategic alignment becomes
particularly important during what many treasury professionals describe as the
current "shoulder period" of the interest rate cycle.
With central bank policy becoming
increasingly data dependent, institutions face growing pressure to protect
margins without exposing themselves to unnecessary interest rate risk.
Rather than attempting to predict a
single direction for rates, Bublic believes flexibility should become the
overriding objective.
"The key in the shoulder period
is disciplined optionality," he says. "Rather than making large
directional bets on the rate path, institutions should ladder asset maturities,
diversify funding, and preserve flexibility to act as opportunities
emerge."
He also argues that existing hedging
strategies should not simply roll forward unchanged.
"Deposit pricing strategies
deserve critical reassessment, and existing hedge positions should be
recalibrated to reflect updated rate expectations rather than rolled over
mechanically," Bublic says.
"Agility and scenario
preparedness matter more right now than conviction on a single outcome."
Deposits remain one of the most
important foundations of banking resilience, but Bublic believes many
institutions still focus too heavily on pricing rather than customer
relationships.
"Stable deposits come from a
value proposition that goes beyond rate," he says.
"Price-sensitive customers
attracted solely by rate will leave when a better offer appears - genuine
stickiness comes from the quality of the overall relationship: transaction
accounts, service breadth, and long-term trust."